What Is the Step-by-Step Process to Buy a House in the UK?
Moving to the UK and dreaming of owning your own piece of British real estate can feel like navigating a particularly twisty, ancient country lane in the dark. The process often feels opaque and unnecessarily complex, leaving many expats scratching their heads and wondering if they'll ever get to plant roots. Fear not, fellow adventurer! This guide will break down the entire step-by-step process of buying a house in the UK, helping you understand each stage, from initial financial planning to finally getting those coveted keys in your hand.
Understanding the UK Property Landscape as an Expat
The UK property market, with its unique terminology and entrenched practices, can be a steep learning curve for anyone, let alone an expat. It’s not just about finding a house; it's about understanding the ecosystem, the players involved, and the unspoken rules. You're probably used to a different system entirely, and the sheer volume of information, often presented in baffling legalese, can be truly overwhelming.
Initial Considerations and Research
Before you even start looking at charming cottages or sleek city flats, you need to arm yourself with knowledge. This isn't just about what you want, but what the UK market expects from you and how you can best navigate it. Many expats jump straight into property portals, only to find themselves frustrated when they don't understand the underlying requirements. Take a deep breath and start with the fundamentals.
Firstly, immerse yourself in understanding the different types of property ownership in the UK. Are you looking at a freehold, where you own the building and the land it sits on outright? Or perhaps a leasehold, common for flats, where you own the property for a fixed period but not the land, and often pay ground rent and service charges? This distinction is crucial and can significantly impact future costs and control over your home. It's really worth diving into what these mean for you, especially if you're not familiar with them from your home country. For a deeper dive, check out our guide on Understanding Leasehold vs Freehold Property in the UK (2027).
Next, research the areas that truly appeal to you, considering your lifestyle, work, and family needs. London is often the first thought, but its diverse boroughs come with vastly different price tags and vibes. Outside the capital, vibrant cities like Manchester, Birmingham, Edinburgh, and Bristol offer fantastic opportunities and often more affordable living. Think about commuting routes, local amenities, school catchment areas if you have children, and community feel. It's not just about the house; it's about the life you'll lead there. Spend time exploring these locations online, using tools like Google Street View, and if possible, plan a few reconnaissance trips.
Financial Groundwork: Mortgages and Deposits
This is arguably the most crucial and often the most challenging part for expats. Securing a mortgage in the UK isn't always straightforward if you're new to the country or don't have a long credit history here. Lenders can be cautious, and requirements might seem dauntingly stringent compared to what you're used to. It's easy to feel like you're running up against a brick wall, but with the right approach, it's entirely achievable.
Your deposit is the cornerstone of your purchase. Generally, you'll need at least a 5-10% deposit for a residential mortgage, but having more (15-20% or even higher) can open up better interest rates and more lender options. Remember that the larger your deposit, the less you need to borrow, which can save you a substantial amount in interest over the mortgage term. Gather all your financial documents – proof of income, bank statements, identification, and any existing credit reports from your home country. Be prepared to explain the source of your deposit, especially if it's coming from overseas.
Getting an Agreement in Principle (AIP) or Decision in Principle (DIP) from a lender is an essential early step. This is a non-binding estimate of how much a lender might be willing to lend you, based on an initial assessment of your finances. It shows sellers and estate agents that you're a serious buyer and can move forward with a purchase. Many agents won't even entertain an offer without one. Navigating the complexities of borrowing as a non-resident requires specialist knowledge, so consulting a mortgage broker who understands the expat market is highly recommended. They can help you understand Understanding Mortgages and Deposit Requirements in the UK and guide you through the various products available. For those ready to apply, our guide on How to Get a Mortgage to Buy a Home in the UK provides a detailed walkthrough.
The Hunt for Your Dream UK Home
Once your finances are in order and you know where you want to live, the exciting part begins: the house hunt! This stage requires patience, a keen eye, and a good working relationship with those on the ground. You'll quickly realise that the UK housing market moves fast, and properties can be snapped up before you even have a chance to view them.
Engaging with Estate Agents
In the UK, estate agents primarily work for the seller, so keep that in mind. Their goal is to achieve the best possible price for their client, but they are also a crucial conduit for you, the buyer. You’ll want to register with several reputable estate agents in your target areas. Don't just rely on national portals; many local agents have properties that might not appear everywhere online immediately. Give them a clear brief of what you’re looking for: number of bedrooms, desired location specifics, budget range, and any must-have features.
A good estate agent can be invaluable. They can alert you to new properties before they even hit the main websites, offering you a crucial head start in a competitive market. They can also offer insights into local areas, recent sale prices, and provide guidance on the offering process. While their primary loyalty is to the seller, a smart agent understands that a smooth transaction benefits everyone. Don't be afraid to ask questions, even if they seem basic – remembering that you're an expat figuring things out will generally elicit a more helpful response. For more advice on this, you might find our article How Do I Find an Estate Agent in the UK? useful.
You'll also need to stay connected during your property search. Having reliable internet access on the go is essential for checking new listings, researching areas, and communicating with agents. Consider a portable Wi-Fi solution or an eSIM from a provider like Airalo to ensure you're always online without relying on patchy public hotspots, especially when you're out viewing properties.
Viewing Properties and Making an Offer
This is where your research pays off. When viewing properties, try to see beyond the staging. Look at the condition of the roof, windows, and any signs of damp or structural issues. Test taps, flush toilets, and check the boiler if possible. Ask about the age of the heating system, recent renovations, and utility costs. Don't be shy; this is a huge investment. A second viewing is often a good idea, perhaps at a different time of day, to get a better feel for light and noise levels.
Once you find a property you love, it’s time to make an offer. This is typically done verbally through the estate agent, who will then relay it to the seller. Your offer should be backed by your Agreement in Principle and clearly state any conditions, such as it being subject to a survey. Be prepared for negotiation. In a seller’s market, you might need to offer close to or even over the asking price, especially in popular areas. In a buyer's market, you might have more room to haggle. The agent should communicate all offers to the seller, and they are legally obliged to do so. They'll also check your readiness to proceed, so having your AIP ready is key. Remember, until contracts are exchanged, nothing is legally binding, and either party can pull out – a concept known as "gazumping" or "gazundering," which can be incredibly frustrating.
Navigating the Legal and Administrative Maze
After your offer is accepted, you enter the formal process. This is where things can feel like they slow down significantly, and the complexities of UK property law come into play. You'll be dealing with solicitors, surveyors, and a whole host of paperwork. It’s a marathon, not a sprint, and staying organised and proactive is paramount.
Conveyancing: The Legal Back-and-Forth
Conveyancing is the legal process of transferring ownership of a property from one person to another. You absolutely need a solicitor or licensed conveyancer to act on your behalf. They will handle all the legal aspects, including contract drafting, conducting searches, checking the property's title deeds, and managing the transfer of funds. It's crucial to choose a good, proactive solicitor. A slow solicitor can hold up the entire chain, causing immense stress. Ask for recommendations, check reviews, and ensure they specialise in residential property.
Your solicitor will work through a series of steps:
- Draft Contracts: The seller's solicitor will draft the contract of sale and send it to your solicitor.
- Enquiries: Your solicitor will raise enquiries with the seller’s solicitor, asking for clarification on various aspects of the property, from boundaries to planning permissions. This can involve a lot of back-and-forth.
- Searches: These are checks made with local authorities and other bodies to uncover any issues that might affect the property, such as planning proposals, flood risks, or contamination. These searches are vital for protecting your investment.
- Mortgage Offer: If you're getting a mortgage, your lender will issue a formal mortgage offer after their own valuation of the property. Your solicitor will then review this.
This stage demands a lot of paperwork. Make sure you have all your personal and financial documents ready. For a comprehensive list, our article What Documents Do I Need to Buy a House in the UK? will be incredibly helpful. Keeping track of all communications and documents is critical. Many property purchases fall through during this phase due to delays or unforeseen issues, so persistent communication with your solicitor is key. For a complete understanding of this legal minefield, read our detailed guide on How to Complete the Conveyancing Process When Buying in the UK.
Surveys, Searches, and Stamp Duty
Beyond the legal searches, it is highly recommended to commission an independent property survey. A mortgage lender will arrange a basic valuation survey to protect their interest, but this often won't reveal underlying problems that could cost you thousands later. There are different types of surveys:
- RICS HomeBuyer Report: Suitable for conventional properties in reasonable condition, highlighting urgent defects and potential legal issues.
- RICS Building Survey (formerly Full Structural Survey): Recommended for older, larger, or non-standard construction properties, providing an in-depth analysis of the property's structure and condition.
The survey can uncover issues that allow you to renegotiate the price or ask the seller to fix them. If significant problems arise, you might even decide to pull out of the purchase, which, while disappointing, is better than buying a money pit.
Then there's the dreaded Stamp Duty Land Tax (SDLT). This is a tax you pay when you buy a property or land over a certain price in England and Northern Ireland. Different rates apply for Scotland (Land and Buildings Transaction Tax, LBTT) and Wales (Land Transaction Tax, LTT). The amount you pay depends on the property price, whether you're a first-time buyer, and if you own other properties. Expats, particularly those who already own property abroad, might face higher rates. It's an unavoidable cost that can significantly add to your overall expenses, so factor it into your budget from the very beginning. You can learn more about this by reading How Much Is Stamp Duty on a House in the UK?.
Here’s a simplified breakdown of the Stamp Duty Land Tax rates in England (accurate as of early 2024, but always check current government guidelines):
| Purchase Price Segment | Standard Rate (%) | First-Time Buyer Rate (%) | Non-UK Resident Surcharge (%) |
|---|---|---|---|
| Up to £250,000 | 0 | 0 | +2 |
| The next £675,000 (from £250,001 to £925,000) | 5 | 5 | +2 |
| The next £575,000 (from £925,001 to £1.5m) | 10 | 10 | +2 |
| The remaining amount (over £1.5m) | 12 | 12 | +2 |
Note: The first-time buyer relief applies to purchases up to £625,000. If the property is over £625,000, you cannot claim first-time buyer relief and will pay the standard rates. Non-UK residents pay an additional 2% surcharge on top of the standard rates if buying a residential property in England or Northern Ireland.
The total costs associated with buying a house in the UK can be substantial, beyond just the purchase price. From solicitor fees to survey costs, mortgage arrangement fees, and Stamp Duty, it's easy to overlook these until they hit. We highly recommend checking out our articles How Much Are the Costs to Buy a House in the UK? and How Do I Calculate the True Cost of Buying a House in the UK? to ensure you're fully prepared.
Exchange, Completion, and Moving In
You're almost there! This is the home stretch, where everything becomes legally binding, and the finish line is finally in sight. After weeks or months of waiting, it’s a moment of immense relief, mixed with the inevitable stress of moving.
Exchanging Contracts and Final Preparations
The exchange of contracts is the point of no return. This is when you and the seller legally commit to the sale. Your solicitor will guide you through this, but essentially, once contracts are exchanged, you are legally bound to buy the property and the seller is legally bound to sell it. If you pull out after this stage, you'll lose your deposit (typically 10% of the purchase price). The completion date is usually set at this point, often 1-4 weeks after exchange.
Before exchange, ensure all conditions are met: your mortgage offer is firm, your survey is satisfactory, and all enquiries have been answered. You’ll also need to have buildings insurance in place from the date of exchange, not completion, as you become responsible for the property from that moment. It's a surreal feeling, knowing that you've committed to such a massive purchase.
Leading up to completion, you'll need to start thinking about the practicalities of moving. Not just packing boxes, but notifying utility providers, redirecting mail, and arranging for your belongings to be moved. If you’re relocating internationally, a specialist moving company like Sirelo can be a godsend, handling the logistics of shipping your possessions across borders. They can make the daunting task of moving all your worldly goods feel a lot less stressful.
Completion Day: Keys in Hand
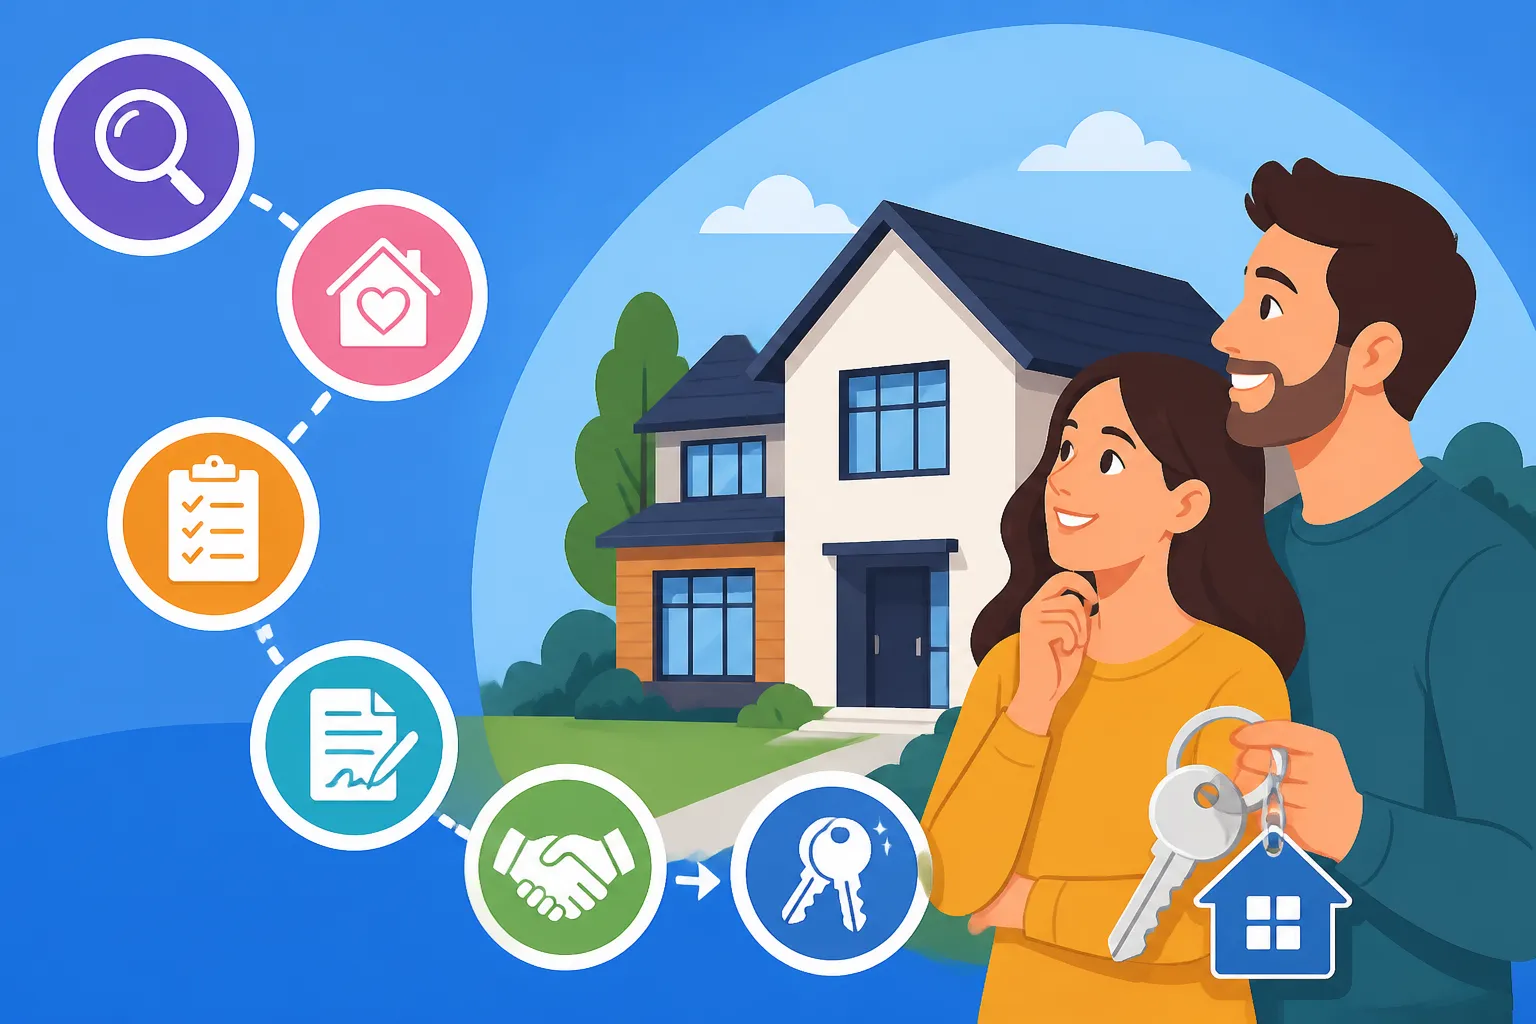
This is the day you've been dreaming about! On completion day, your solicitor transfers the remaining balance of the purchase price to the seller's solicitor. Once the funds are received and confirmed, the seller's solicitor will authorise the release of the keys. You'll typically collect these from the estate agent.
Once you have the keys, the property is officially yours! You can now move in, unpack, and start making it your home. Don't forget to take meter readings for gas, electricity, and water as soon as you get in, and contact the utility companies to set up your accounts. You’ll also need to register for Council Tax with the local authority. It's a whirlwind of activity, but the sense of accomplishment is unparalleled. Congratulations, you've successfully bought a house in the UK!
The journey of buying a home in the UK as an expat is certainly unique and can be a bit of a rollercoaster. There will be moments of confusion, frustration, and perhaps even despair. But with careful planning, robust research, and the right professional support, it is absolutely an achievable dream. Knowing the steps, understanding the local quirks, and staying patient will be your biggest assets. Welcome home! Our comprehensive guide on The Complete Guide to Moving to the UK: Your First 90 Days (2027) offers further assistance for your initial settlement.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.